


“Sharq bahori” mortgage loans
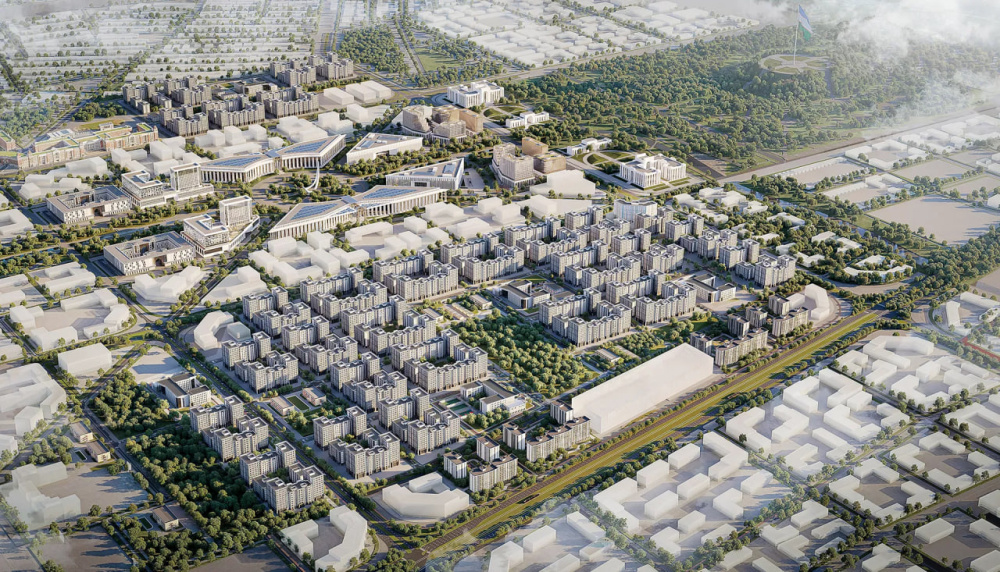
Private Joint-Stock Bank “Trustbank” has launched the issuance of mortgage loans to individuals for the purchase of apartments (on equity participation terms) in the residential complex “Sharq bahori” under construction by the State Institution “Directorate for the Construction of New Tashkent” on the territory of Yukori Chirchik and Urta Chirchik districts of Tashkent region adjacent to the city of Tashkent, with a total area of 19,720.9 hectares.Visit our banking offices, complete the paperwork in a short time, and own the home of your dreams. The loan does not have a grace period.
Terms of the “Sharq bahori-1” mortgage loan
|
No. |
Indicator name |
Terms |
|
|
1 |
Client |
Individual (citizen of the Republic of Uzbekistan) |
|
|
2 |
Loan purpose |
Purchase of housing (an apartment) in the “Sharq bahori” residential complex being built by the New Tashkent City Development Directorate state institution |
|
|
3 |
Maximum loan amount |
up to UZS 900.0 million |
|
|
3.1 |
Depending on the funding source (hybrid method) |
From MEF (Ministry of Economy and Finance) resources |
From the bank's funds |
|
up to UZS 420.0 million |
up to UZS 480.0 million |
||
|
If a mortgage loan is not disbursed under the hybrid method, up to UZS 480 million from MEF funds (in this case, no mortgage loan is disbursed from the bank’s funds) |
|||
|
Should the maximum amount of mortgage loan refinancing approved by a decree or resolution of the President of the Republic of Uzbekistan and/or a resolution of the Cabinet of Ministers change in the future, the established limit amount will be changed accordingly. |
|||
|
4 |
Down payment |
For the portion allocated from MEF resources |
For the portion allocated from the bank's funds |
|
15 percent |
20 percent |
||
|
(in this case, payments made toward the apartment price at auction may also be accepted as the down payment) |
|||
|
5 |
Annual interest rate |
For clients with a steady income |
|
|
From MEF (Ministry of Economy and Finance) resources |
From the bank's funds |
||
|
16.8 percent |
17 percent |
||
|
For self-employed clients |
|||
|
From MEF (Ministry of Economy and Finance) resources |
From the bank's funds |
||
|
16.8 percent |
18 percent |
||
|
5.1 |
Interest calculation terms — fixed or variable |
Variable: if, after the cadastral documents for the apartment purchased with the loan have been drawn up and state-registered, the borrower fails to pledge the apartment to the bank within 20 days in the established manner, the loan's annual interest rate (until the pledge is made) changes to 25 percent. This condition must be stated in the loan agreement. |
|
|
6 |
Term |
For a term of no more than 240 months. |
|
|
7 |
Borrower age requirement |
Being at least 18 and not more than 60 years of age (60 years inclusive) on the date of applying for the loan. (it must be taken into account that the age must not exceed 60 years at the time of refinancing by the Ministry of Economy and Finance) |
|
|
8 |
Eligibility criteria for borrowers/co-borrowers (individuals):
|
- having permanent employment and a source of income sufficient to pay the accrued interest and principal on the loan monthly in accordance with the repayment schedule; - the debt burden ratio must not exceed 50 percent. - no overdue debt to the bank or other credit institutions at the time the mortgage loan application is reviewed. - using a mortgage loan allocated under this program for the first time (in this case, mortgage loans obtained by the borrower before 1 May 2024 are not taken into account) |
|
|
9 |
Loan-to-value (LTV) ratio |
For the portion allocated from Ministry of Economy and Finance funds
LTV≤85% |
For the portion allocated from the bank's own funds
LTV≤80%. |
|
10 |
Delivery of housing (submission to the bank as collateral) |
By the end of Q2 2027. |
|
|
11 |
Repayment method |
Annuity or differentiated method |
|
|
12 |
Number of co-borrowers |
up to 4 persons |
|
|
13 |
Collateral |
- the housing (apartment) purchased with the loan. - until the construction of the housing purchased with the loan is completed, the cadastral documents are drawn up and it is pledged as collateral, a guarantee from the New Tashkent City Development Directorate for an amount of not less than 125 percent of the loan amount is accepted. Once construction is completed and the cadastral documents are drawn up, the collateral for the loan is replaced by a mortgage on this housing. |
|
|
14 |
Other conditions |
1. A continuous delay of 90 (ninety) days by the client in loan payments during the period from when the mortgage loan is disbursed to the client until the housing (apartment) purchased with the loan is fully registered with cadastral documents and pledged as collateral shall be grounds for the bank to unilaterally terminate the mortgage loan agreement concluded with the client, and for the loan payments to be fully repaid from the funds of the “New Tashkent City Development Directorate.” |
|
Terms of the “Sharq bahori-2” mortgage loan
|
No. |
Indicator name |
Terms |
|
|
1 |
Client |
Individual (citizen of the Republic of Uzbekistan) |
|
|
2 |
Loan purpose |
Purchase of housing (an apartment) in the “Sharq bahori” residential complex being built by the New Tashkent City Development Directorate state institution |
|
|
3 |
Maximum loan amount |
in an amount not exceeding UZS 800.0 million |
|
|
4 |
Funding source |
From the bank's own funds |
|
|
5 |
Term |
For a term of no more than 120 months. |
|
|
6 |
Down payment
|
For those with a steady income |
For the self-employed |
|
20 percent |
20 percent |
||
|
(in this case, payments made toward the apartment price at auction may also be accepted as the down payment) |
|||
|
7 |
Annual interest rate |
With a steady income |
Self-employed |
|
23 percent |
24 percent |
||
|
8 |
Borrower age requirement |
Being at least 18 and not more than 60 years of age (60 years inclusive) on the date of applying for the loan.
|
|
|
9 |
Eligibility criteria for borrowers/co-borrowers (individuals) |
- having permanent employment and a source of income sufficient to pay the accrued interest and principal on the loan monthly in accordance with the repayment schedule; - the debt burden ratio must not exceed 50 percent. - no overdue debt to the bank or other credit institutions at the time the mortgage loan application is reviewed. |
|
|
10 |
Loan-to-value (LTV) ratio |
LTV≤80%.
|
|
|
11 |
Delivery of housing (submission to the bank as collateral) |
By the end of Q2 2027 |
|
|
12 |
Repayment method |
Annuity or differentiated method |
|
|
13 |
Number of co-borrowers |
up to 4 persons |
|
|
14 |
Collateral |
- the housing (apartment) purchased with the loan. - until the construction of the housing purchased with the loan is completed, the cadastral documents are drawn up and it is pledged as collateral, a guarantee from the New Tashkent City Development Directorate for an amount of not less than 125 percent of the loan amount is accepted. Once construction is completed and the cadastral documents are drawn up, the collateral for the loan is replaced by a mortgage on this housing. |
|
|
15 |
Other conditions |
A continuous delay of 90 (ninety) days by the client in loan payments during the period from when the mortgage loan is disbursed to the client until the housing (apartment) purchased with the loan is fully registered with cadastral documents and pledged as collateral shall be grounds for the bank to unilaterally terminate the mortgage loan agreement concluded with the client, and for the loan payments to be fully repaid from the funds of the “New Tashkent City Development Directorate.” |
|
Information sheet on the main terms of the credit (Sharq bahori -1)
Information sheet on the main terms of the credit (Sharq bahori -2)
Sample form of mortgage loan agreement "Sharq bahori" (download)
Sample form of mortgage loan agreement "Sharq bahori" (download)
CHECKLIST provided to the borrower/client prior to execution of the mortgage loan agreement


